Back to overview

Chapter 02 · Member journeys

How Loqbox supports different member needs

Building a credit footprint: thin file and new to credit members

Our analysis showed that members came from a wide range of backgrounds, income levels and financial starting points, with different reasons for joining Loqbox.

This section combines individual case studies with quantitative findings to examine how Loqbox supports three groups: people who are new to credit or have thin credit files, people rebuilding after adverse credit, and people with mainstream credit profiles working towards longer-term goals.

Across these groups, Loqbox aims to help members strengthen their credit profile, develop financial knowledge and confidence, and widen their prospects of accessing appropriate, affordable products.

Credit invisible consumers have little or no credit history, while thin file consumers have some recorded credit information but not enough to give lenders a detailed picture of how they manage credit. This does not mean they are unable to borrow responsibly. However, without sufficient information on which to assess their creditworthiness, lenders may treat them as higher risk even when they have managed their finances responsibly.

In 2023, Experian estimated that between four and five million people in the UK were credit invisible because they had little or no financial data. Experian highlighted three groups commonly affected:

Young people who have not yet established a credit record.

Older people who have paid off their mortgage and make limited use of credit, or who have not previously relied on credit.

Recent immigrants and some returning expatriates who have little or no UK credit footprint.1

Credit invisibility can affect more than someone’s ability to borrow. It may also make it harder to access everyday services involving identity verification or credit checks, including some mobile phone, broadband and rental agreements.

“

I couldn’t get a phone contract. Wi-Fi I couldn’t really get either... I couldn’t do anything... I had to really, really budget just to make sure I got a new phone.

Michael

Impact Report Contributor (Internal Case Study, 2026)

“

I had a really poor credit score from just doing nothing. I’ve paid all my bills on time and nothing missed. So this [Loqbox] was a great way without taking on a credit card to build my credit score.

Internal Loqbox Member Survey Respondent

March 2026

“

Just separated from a 45 year marriage and found myself with no credit score as such due to my husband’s mismanagement of our finances.

Internal Loqbox Member Survey Respondent

March 2026

Strong credit score improvements

Over 12 months, thin file / new to credit Loqbox members who did not miss payments to us, or any other accounts, increased their credit score by an average of 87 points, versus no increase in the control group.

The movement between risk bands matters more than the average.

Among all thin file and new to credit members, the share with a sub-prime score fell from around 35% at sign-up to 24% after a year and 21.5% after two years. Over the same period, the share holding a prime or better score rose from around 22% to 38%.

This shift is consistent with members demonstrating the characteristics of better borrowers and, as better borrowers, gaining access to credit that more accurately reflects their capabilities and behaviours.

Credit card holding more than tripled

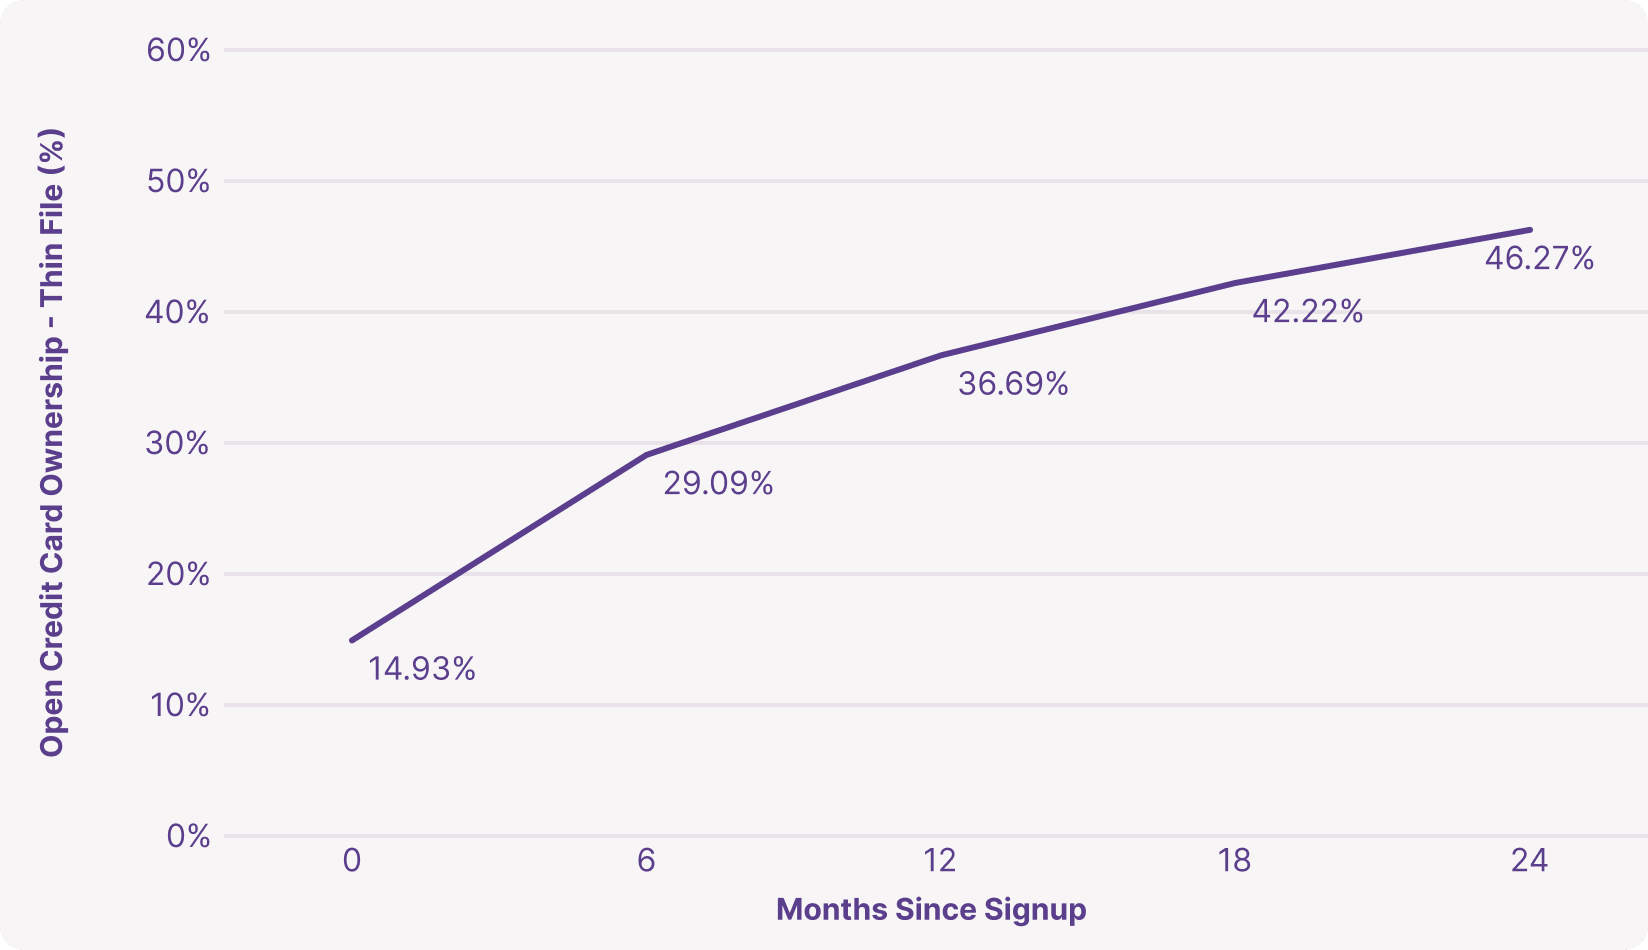
Improvements in members’ credit profiles were accompanied by a substantial increase in credit card holding. The proportion of thin file Loqbox members with an open credit card rose from approximately 15% to over 46%. By comparison, the control group increased by only seven percentage points.

Chart showing credit card holding among thin file Loqbox members rising from around 15% to over 46%, compared with the control group

Source: Loqbox internal analysis

Average credit limits among these same members also increased by approximately £320 over two years, while the control group recorded a decrease of £130. Together, these findings indicate that members’ stronger credit profiles were associated with greater access to mainstream credit.

“

Within 3 months of having Loqbox, I was able to get a credit card... My credit score was like 204 and it went up to 311 within 3 months.

Amy

Impact Report Contributor (Internal Case Study, 2026)

Michael’s story

From credit invisible to greater financial independence

Michael studied Economics and Finance at the University of Derby. After graduating, he began trying to establish himself financially, but found that his limited credit history prevented him from accessing everyday services in his own name.

“It's not that I'm not able to do it, or I'm not capable of doing it, just that the system's saying no.”

Michael had previously used a pay as you go mobile and had not needed credit. But when he applied for a phone contract and broadband, he was declined. He had to buy phones outright and arrange Wi-Fi through his parents’ account, despite having the income to make the payments himself.

“Simply because [I had] no history. I had no phone bills in my name, no credit cards, nothing. So because I had no credit history, I couldn’t really do anything.”

Michael described feeling trapped: he needed a credit history to access products, but could not access the products through which he might establish that history. His older sister had experienced a similar problem and recommended Loqbox.

Read the full story
+

Explore the report

Loqbox Impact Report 2026

Download the full report

…or talk to us about partnering.