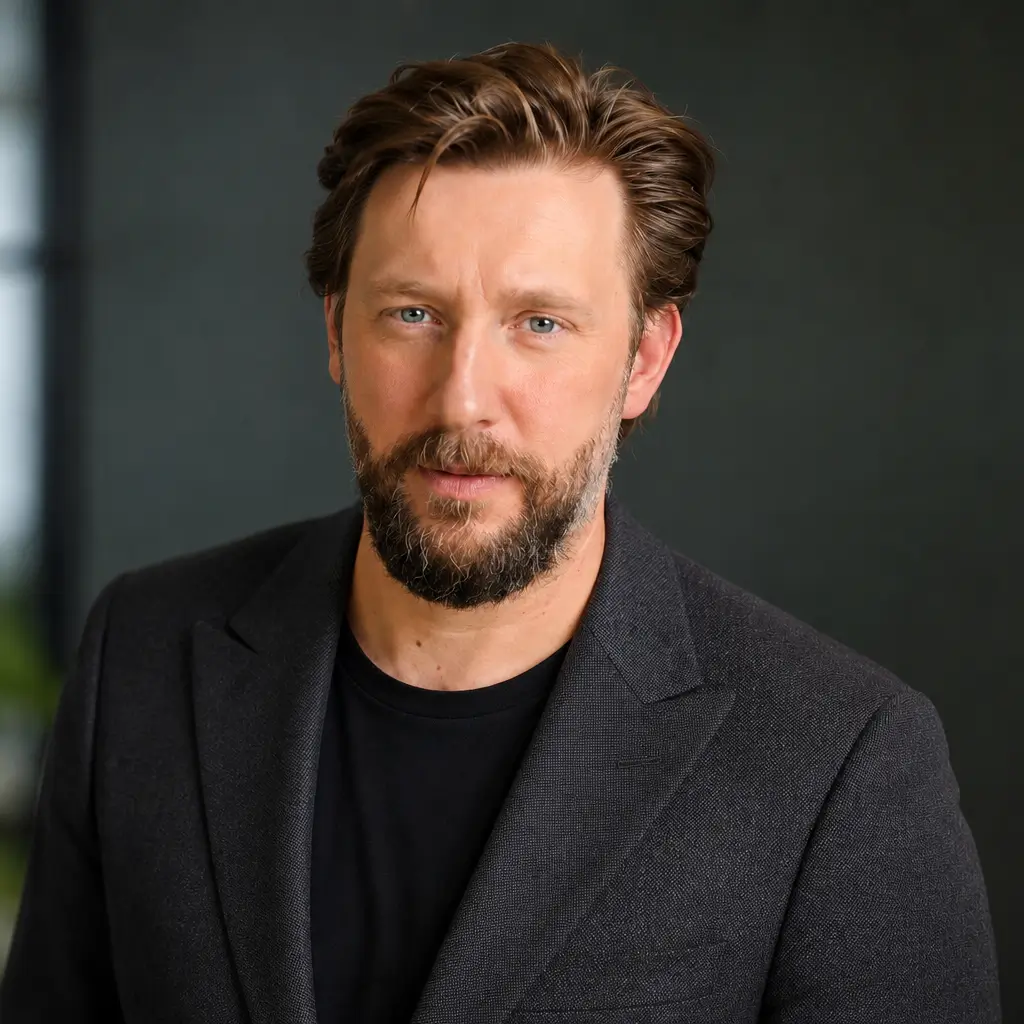

Your credit score can be useful, but the number you see is only part of the picture. Loqbox CEO and Co-Founder Tom Eyre explains what your credit score tells you, why your credit report matters more, and what to do if your score changes.
I’ve spent over a decade building Loqbox and, perhaps unsurprisingly, quite a lot of that time improving understanding about how we use credit, and how it affects our financial lives.
I often think about how much value people place on the scores themselves, and whether we need to do more to help people understand how lenders use the information that sits behind them.
There's a big credit score myth we need to address. A lender is not looking at your credit score and using it to decide whether they'll lend to you or not.
I understand why people think that. You open an app, there’s a big number sitting there, and it goes up or down. It can feel like a mark out of 999 about how well you’re doing with money, and how likely you’ll be approved or rejected.
In some ways, it is. Your score is designed to give you an indication of your creditworthiness based on the information in your credit report. But the number is purely there to help you make sense of the information a CRA holds about you at a specific moment in time.
Lenders look beyond your credit score at the information in your credit report alongside their own criteria when deciding whether to lend to you.
What does your credit score tell you?
Your credit scores are numbers generated by the credit reference agencies (CRAs) to help you understand your credit report. Each CRA takes the information it holds about you and calculates its own score.
Three CRAs, three different credit scores
There are three main CRAs in the UK: Experian, Equifax and TransUnion. You may have different credit scores and bands with each because each CRA has its own scoring system.
The CRAs don’t necessarily hold exactly the same information about you either, because lenders and other providers may report to one, two or all three, so there isn’t one universal credit score.
The useful bit is what sits behind it. Your credit report shows things like your accounts, payments, applications and searches.
Your credit report is more important than your score
When I spoke to The Guardian, I put it simply: “it’s far more important to understand what’s in your report and what shapes it than to worry about a particular band or number.”
It’s worth checking your credit reports with all three of the main CRAs — Equifax, Experian and TransUnion.
Make sure:
- All the accounts listed belong to you, and the balances look right
- Your payment history is correct
- You recognise any applications and searches on your report
- Your address history is up to date
- Your electoral roll information is right
Checking for mistakes is probably the most important first step. As long as what you see on each credit file is technically accurate, it won't matter which CRA an individual lender uses.
It’s worth noting that currently, not every lender is required to report to all three major CRAs, this means that some of your accounts or history may be missing from some CRAs (although this is becoming less common these days).
Treat your score as a starting point, and build from there
Your score and credit bands like “low” and “excellent”, can help you understand your creditworthiness and how lenders might view you, but they don’t give you the full picture, and I think the language used for the bands can sometimes be unhelpful.
If you open an app and it tells you your credit score is “Poor” or “Very Poor”, it’s easy to read it as a judgement on you. It isn’t; it’s simply a summary of where your credit profile sits today.
Nearly half (49%) of Gen Z adults we surveyed worry their credit history could stop them renting or buying a home, so the language we use around credit matters.
That’s one of the things I like about TransUnion moving from “Poor” and “Very Poor” to “Low” and “Very Low”. It sounds like a small change, but I think it’s a helpful reminder that your credit score is a starting point, not a verdict.
What is changing with TransUnion credit scores?
TransUnion is moving its UK consumer credit score from 0–710 to 0–999, with new score bands and a model designed to reflect how people manage credit over time.
Why has my TransUnion credit score changed?
If your score suddenly moves up or down, it’s natural to assume something about your creditworthiness has changed too, but that isn’t always the case.
Under the new model, TransUnion expect 36% of people to move into a higher band and 6% into a lower one.
That’s because TransUnion’s new score model looks at a broader range of information, including how your balances change and how you use credit cards over time, as well as what your credit profile looks like today.
But if a new model moves you into a lower band, it doesn’t mean you’ve become less creditworthy overnight. Your behaviour and your history are the same, what has changed is how TransUnion calculates or presents your score.
If you notice that since you've changed bands, your borrowing options are fewer or more expensive, it's worth further investigation. Look at your credit files to see if something else has changed.
There’s a lot to like in what TransUnion is trying to do here. The new score looks at a broader range of behaviour over time, rather than relying only on a snapshot, and it’s designed to give you clearer information about what’s influencing your credit profile. That feels like a sensible direction of travel to me.
The move from “Poor” to “Low” is a good one. “Low” tells you where a score sits today without feeling like a judgment. Your past credit history is useful, and lenders will pay attention to it, but it’s important to view your current position as a starting point and build from there.
Build the history behind the score
If you’re trying to improve your creditworthiness, it’s very easy to focus on getting your score from one number to another. But the score is only there to help you understand the information held about you; what you’re really building is a financial track record.
That happens over time, through things like making payments when they’re due and managing your financial commitments responsibly. And you don’t need a credit card to do it: phone contracts, utility bills, rent payments — if you report them to the credit reference agencies — can help you build your credit history.
Credit cards aren’t the only option
I spoke about this recently on The Payments Shed, a financial services podcast. I'm all for credit cards, but I find it frustrating that in 2026 the standard advice most people give people wanting to build a credit history is to take out a high-cost credit card.
There need to be more alternatives. 4 million people in the UK have a subprime credit card, and 79% of StepChange clients with one felt it had a negative impact on their financial situation. That’s one of the reasons we created Loqbox: to give people a fairer way to build a credit history, while building their savings and financial confidence.
It comes back to something I’ve talked about before: building better borrowers, not just better credit scores. Your score improving can be a useful sign that you’re moving in the right direction, but the history you’re building underneath it matters more.
Your credit score tells you where you are today, you decide where you go next. Read our blog to find out what to do if your credit score has changed.
Tom recently discussed this topic with Zoe Wood at The Guardian